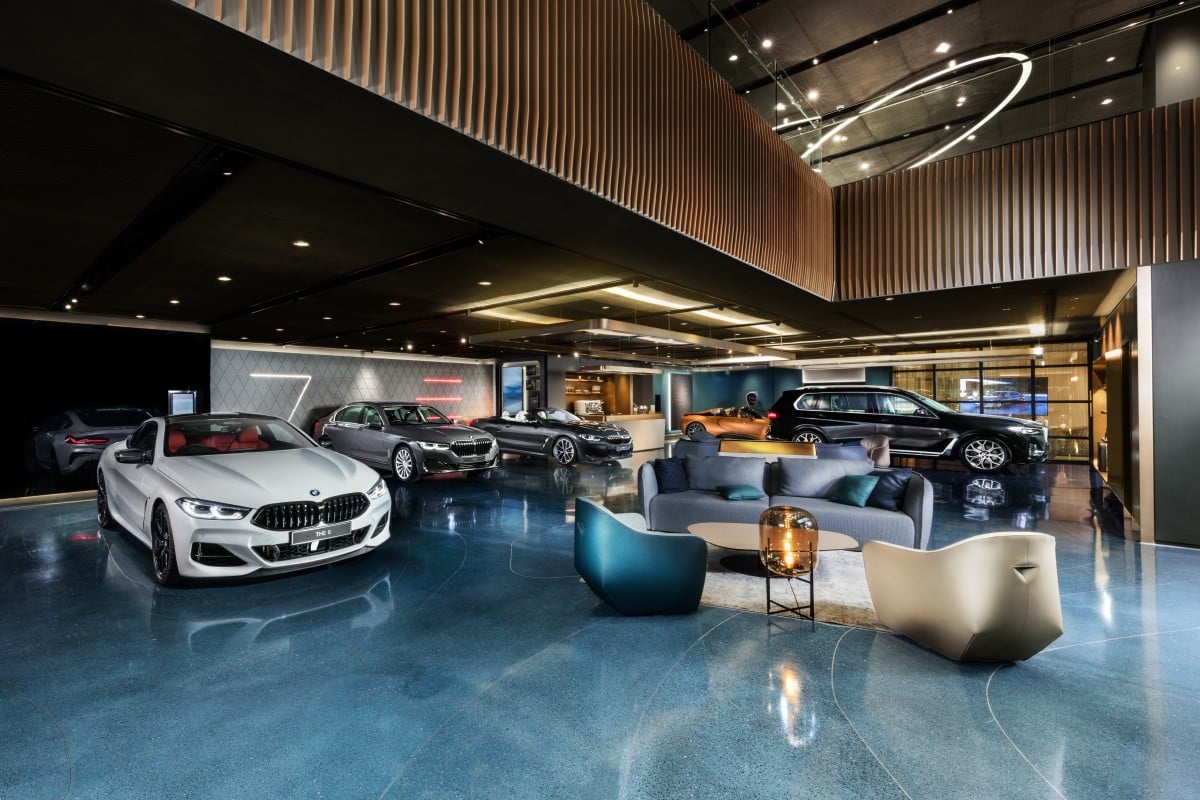
Global luxury automotive manufacturers and premium performance brands are re-engineering their manufacturing ecosystems and research pipelines to focus on ultra-exclusive coachbuilding, highly personalized client commissioning programs, and advanced solid-state battery architecture. Financial disclosures from premier vehicle groups indicate that while mass-market electrification curves have experienced localized plateaus, demand among ultra-high-net-worth buyers for bespoke, low-volume automotive commissions remains exceptionally strong. Engineering teams are concurrently directing research capital toward solid-state battery chemistry and lightweight composite materials to enhance vehicle performance and range capabilities without compromising traditional luxury craftsmanship standards. Supply chain managers report closer collaboration with specialized tier-one component makers to secure traceable raw materials and proprietary electronic control units. Equity analysts note that this strategic bifurcation insulates high-end automotive groups from volume-driven margin pressures in standard consumer segments, preserving robust operating profitability and pricing power across exclusive product portfolios.
The wider context
The immediate question is not simply what happened, but why this development matters now. Global luxury automotive manufacturers and premium performance brands are re-engineering their manufacturing ecosystems and research pipelines to focus on ultra-exclusive coachbuilding, highly personalized client commissioning programs, and advanced solid-state battery architecture. Financial disclosures from premier vehicle groups indicate that while mass-market electrification curves have experienced localized plateaus, demand among ultra-high-net-worth buyers for bespoke, low-volume automotive commissions remains exceptionally strong. Engineering teams are concurrently directing research capital toward solid-state battery chemistry and lightweight composite materials to enhance vehicle performance and range capabilities without compromising traditional luxury craftsmanship standards. Supply chain managers report closer collaboration with specialized tier-one component makers to secure traceable raw materials and proprietary electronic control units. Equity analysts note that this strategic bifurcation insulates high-end automotive groups from volume-driven margin pressures in standard consumer segments, preserving robust operating profitability and pricing power across exclusive product portfolios. This combination of near-term evidence and longer-term pressure is changing the way investors frame the story. Rather than treating the headline as a single event, market participants are reading it as a signal about the price of capital, the durability of demand, and the room policymakers have to respond.
The market architecture around global luxury automotive manufacturers pivot toward bespoke customization and solid-state r&d is unusually interconnected. A decision made by a central bank, corporate treasury, producer, or regulator can travel through funding costs, inventory plans, exchange rates, and household expectations before it appears in a conventional economic release. That is why the first reaction can be misleading. A quiet price move may reflect genuine confidence, or it may show that investors are waiting for better confirmation.
Why it matters to markets
For businesses, the practical impact is already visible in planning meetings. Finance teams are revisiting liquidity buffers, procurement contracts, and the timing of capital expenditure. Operators with flexible balance sheets have more choices: they can lock in financing, build strategic inventory, or wait for clearer signals. Smaller participants face a sharper trade-off between protecting margins today and preserving the capacity to invest tomorrow. The quality of execution will matter as much as the direction of the macro trend.
Investors are also separating structural change from cyclical noise. Structural forces tend to alter the economics of an industry for years: supply-chain redesign, energy transition spending, changing work patterns, and the digitization of decision-making all fit that description. Cyclical forces are faster and less reliable, including a temporary inventory build, a seasonal slowdown, or a brief change in risk appetite. The strongest analysis keeps both horizons in view without forcing a dramatic conclusion.
The next set of indicators will help determine whether this is a durable shift. Markets will be watching employment and wage data, auction demand, corporate guidance, credit spreads, physical inventories, and the behavior of end customers. None of these measures is perfect in isolation. Together, however, they can show whether financial conditions are becoming easier or tighter, whether demand is broadening or concentrating, and whether supply is responding quickly enough to absorb the pressure.
What to watch next
There are risks on both sides of the outlook. An unexpectedly strong reading could delay policy relief and lift financing costs, while a sharper slowdown could expose weak balance sheets and fragile business models. Geopolitical events, weather, regulation, and technology bottlenecks add another layer of uncertainty. The prudent response is not to ignore those risks or to predict every turn, but to test how portfolios and operating plans behave across several plausible scenarios.
Our view is that this story deserves attention because it sits at the intersection of immediate market pricing and a broader reallocation of capital. The most valuable signal may not arrive in the next headline. It may emerge gradually in the choices made by lenders, investors, households, and companies as they adapt. That process is often slower than a trading session, but it is what ultimately defines the next financial cycle.
This article is an editorial briefing designed to provide context, not personal investment advice. Read the original evidence, understand the risks, and make decisions appropriate to your own circumstances.